If you were gone, could they keep the house?
The mortgage doesn't stop when an income does. Mortgage protection is life insurance sized to your mortgage, so the balance can be paid to your family tax-free and they stay in the home. Answer 4 quick questions and a licensed broker will call you today with your options.
40 seconds. Then answer 4 quick questions below.
What happens after you hit the button
You answer 4 questions
Mortgage, state, age, and the best time to call. About one minute.
Madison calls you today
From (464) 768-5408. Please answer. A licensed broker, not a call center.
A ten-minute review
What you already have, what your mortgage needs, and what you may qualify for. If it's not a fit, you'll hear that in the first five minutes.
Three things homeowners assume
Mortgage protection fixes that
- If something happens to you, your family receives a tax-free payout sized to the homePaid to your family, not the bank. They decide what to do with it.
- Many policies include optional living-benefit ridersIf the insured is diagnosed with a qualifying serious illness, money may be advanced while you're alive. Varies by carrier and state.
- No medical exam on many optionsApproval may depend on your answers to health questions. Declined before? Different carriers give different answers.
- A licensed broker shops many A-rated carriers for youYou're not locked into one company's rate.
Who will be calling
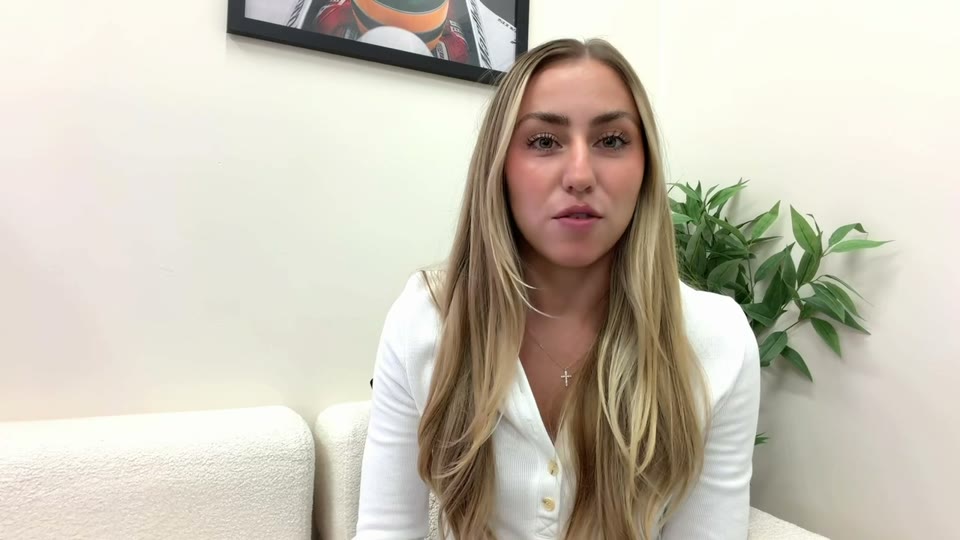
“When you send the form, I'm the one who calls. Ten minutes, no pressure. If I can't help you, I'll say so and we'll hang up as friends.”
Quick answers
How much does it cost?
It depends on your age, health, the amount, and the carrier. Coverage is sized to your mortgage, not to a number picked for you. You'll get real figures on the call, not a teaser.
I have life insurance through work.
Most work policies are one to two times salary and end when the job ends. Ask how many years of your mortgage it would cover. Often it's less than three.
I've been declined or I take medication.
Different carriers underwrite differently. Many options don't require an exam, though approval may depend on your answers to health questions. It's worth a ten-minute look.
Will I get spam calls?
No. Only Madison Wald's office contacts you, from one number, and you can reply STOP to any text at any time. We never sell your information.
Are you my mortgage company?
No. We are an independent life insurance brokerage. We are not affiliated with any lender, bank, or government agency.